Most standard marine cargo insurance in the UAE costs between about 0.05% and 0.35% of a shipment's insured value, with temperature-sensitive and project cargo rated higher and war risk charged on top. On an insured value of AED 220,000, that is roughly AED 110 to AED 770 for the marine cover alone. Your actual marine cargo insurance cost in UAE depends on what you ship, how it travels, the cover you choose and your claims record.
In 2026, war risk has become the most volatile part of the bill for cargo moving through the Strait of Hormuz and the Red Sea. This guide explains how premiums are calculated, the rates to expect by cargo type and how importers can cut cost without weakening cover. All figures are indicative, because cover terms and pricing are individually underwritten.
What Determines Marine Cargo Insurance Cost in UAE
The premium is the insured value multiplied by a rate. Insured value is normally the CIF value (cost, insurance and freight) plus 10%, which allows for incidental costs and the margin you expect to make on the goods. The rate reflects how likely and how severe a loss is for that cargo on that journey.
Step
Example
CIF value of goods
AED 200,000
Insured value (CIF plus 10%)
AED 220,000
Marine rate (illustrative)
0.12%
Marine premium
AED 264
War and strikes premium
Quoted separately for each voyage
The rate itself depends on the cargo and its packing, the clauses you buy (Institute Cargo Clauses A, B or C), the route, the vessel, your deductible and your loss record. Underwriters also look at the final leg. Cargo landed at Jebel Ali or Khalifa Port and held for Dubai Customs or Abu Dhabi clearance faces different handling, storage and theft exposures from cargo trucked in from an east coast port.
Typical Premium Rates by Cargo Type
The ranges below are indicative for Institute Cargo Clauses (A) cover unless stated, before war and strikes. Use them for budgeting, not as a quotation.
Cargo type
Indicative rate (% of insured value)
Key risk factor
Bulk commodities on ICC (B) or (C)
0.03% to 0.10%
Shortage and contamination
General merchandise and FMCG
0.08% to 0.20%
Handling damage and pilferage
Electronics and high-value goods
0.15% to 0.35%
Theft and concealed damage
Temperature-sensitive goods and pharmaceuticals
0.20% to 0.50%
Refrigeration failure and spoilage
Project cargo and machinery
Rated case by case
Lifting, lashing and breakbulk handling
General Merchandise and FMCG
Containerised consumer goods, building materials and packaged food sit at the lower end of the scale. Losses tend to be small and frequent: crushed cartons, water damage and short delivery. A sensible deductible absorbs these and keeps the rate down.
Electronics and High-Value Goods
Phones, laptops, watches, cosmetics and other goods that are easy to resell are rated higher, and sometimes above the range shown. The main concern is theft, often discovered only when a container is opened at the warehouse. Underwriters may ask for high-security seals, GPS tracking, approved hauliers and a limit per container.
Project Cargo and Machinery
Heavy plant, machinery and project cargo are priced individually. Out-of-gauge and breakbulk pieces face lifting, lashing and on-deck stowage risks, so underwriters often require a marine warranty survey for critical lifts and set a higher deductible. Second-hand machinery is frequently insured on restricted terms that exclude mechanical breakdown.
Five Factors That Push Your Premium Up
Route and war risk. Since the conflict that began on 28 February 2026, voyages through the Strait of Hormuz have carried war risk rates far above normal. Hull war rates alone moved from about 0.25% of a ship's value before the war to 3% to 10% in July 2026. Cargo war cover is quoted per voyage, can change at short notice and normally applies only while goods are on the vessel.
Rerouting and transhipment. Many carriers now discharge Gulf-bound cargo at Khor Fakkan, Fujairah or Omani ports, and DP World runs bonded transfers from the east coast to Jebel Ali. Every extra handling, truck leg and storage period adds risk.
Theft-attractive or fragile cargo. Electronics, branded goods and anything easy to resell cost more to insure, as do glass, ceramics and goods that need refrigeration.
Older or unclassed vessels. Under the Institute Classification Clause, cargo carried on older ships or ships not classed by an approved society attracts additional premium.
Claims history and low deductibles. A run of small claims raises the rate at renewal, and a very low deductible means the insurer prices in every minor loss.
How UAE Importers Reduce Cost Without Reducing Cover
Insure on the right value. CIF plus 10% is the market norm. Inflating the value raises the premium without improving what you recover.
Control the cover yourself. Buying on FOB or CFR terms and arranging your own policy avoids relying on a supplier's minimum ICC (C) cover under CIF, which often leaves importers underinsured.
Choose a deductible you can absorb. Taking small, frequent losses yourself can lower the rate.
Pack and stow for the journey. Proper packing, sealed containers and under-deck stowage reduce both claims and rates.
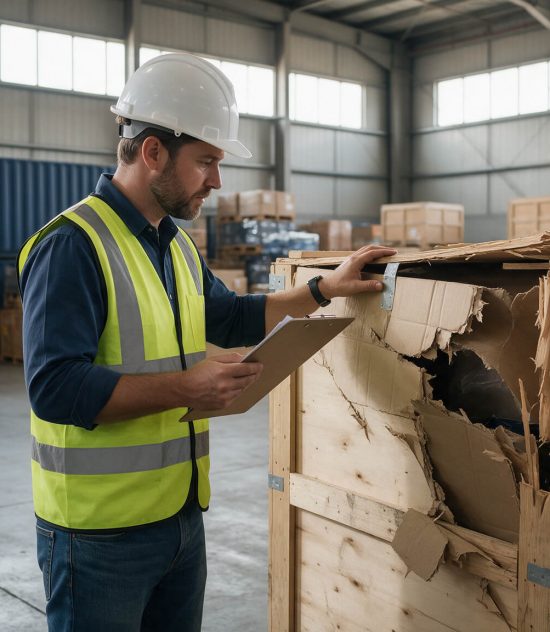
Protect your claims record. Inspect cargo before signing the delivery receipt, note any damage and keep evidence so the insurer can recover from the carrier.
Plan clearance and storage. Standard cover ends 60 days after discharge at the final port. If inspections or trucking delays could hold goods longer, arrange an extension before it runs out.
Act fast on a change of port. If a carrier discharges at a port other than the one on your bill of lading, tell your insurer straight away. Cover normally continues only if you notify promptly and pay any additional premium.
Open Cover vs Per-Shipment: The Cost Difference
Buying marine cargo and goods in transit cover one shipment at a time suits importers who ship occasionally. Each shipment is priced on its own, and single-shipment policies often carry a minimum premium, which makes small consignments relatively expensive.
An annual marine cargo open cover fixes rates and conditions for agreed cargo types and routes for the year. You declare shipments as they move and pay premium on declared values, usually against a deposit. Because the insurer sees your whole programme, rates are usually lower per shipment and fewer shipments slip through uninsured.
Per-shipment
Open cover
Pricing
Quoted each time
Agreed rates for the year
Minimum premium
Often one per shipment
A deposit or annual minimum
Admin
A request for every shipment
Regular declarations
Risk of an uninsured shipment
Higher
Lower, if declarations are made
For importers shipping regularly, open cover is usually cheaper overall. War and strikes rates under either option remain subject to change at short notice.
Frequently Asked Questions
How is marine cargo insurance cost in UAE calculated?
Insurers multiply the insured value, usually the CIF value plus 10%, by a rate set for the cargo, route and cover. War and strikes cover is added separately, and single-shipment policies often carry a minimum premium.
Does marine cargo insurance cover war risk in the Gulf?
Not as standard. War and strikes cover is added through separate clauses, priced per voyage and subject to change at short notice, and war cover normally applies only while goods are on board the vessel.
What happens to my cover if the carrier discharges at Khor Fakkan instead of Jebel Ali?
Under the standard Institute Cargo Clauses, cover can continue when a carrier ends the voyage at a different port, provided you notify the insurer promptly and pay any additional premium requested. Tell your broker as soon as you receive a change of discharge notice.
Is open cover cheaper than single shipment insurance?
Usually, if you ship regularly. Open cover spreads the insurer's risk across your annual volume, which tends to lower the rate and removes per-shipment minimum premiums.
Is marine cargo insurance mandatory for imports into the UAE?
It is not a general legal requirement for importing. However, banks often require it under letters of credit, and many sale contracts make one party responsible for insuring the goods.
Talk to ASIB
Your marine cargo insurance cost in UAE is set by underwriters looking at your own cargo, routes and record, so the ranges here are a starting point rather than a quote. In a year when routes and war rates can change week to week, it pays to arrange marine insurance in the UAE through a broker who watches the market for you.
ASIB has worked with UAE businesses since 2003 and is registered with the Central Bank of the UAE (Registration No. 165). Cover terms and pricing are individually underwritten and regulations change. For a rate on your next shipment or an annual open cover, speak to ASIB's marine team.
The ASIB Insurance Team writes these guides to help individuals and businesses in the UAE understand their cover before they need it. ASIB has arranged personal and commercial insurance in the UAE since 2003, with a team of more than 100 insurance professionals.