You claim marine cargo insurance in the UAE by recording any damage on the delivery receipt, notifying your insurer immediately, arranging a survey, putting the carrier on notice and submitting a complete document pack. Miss one of those steps and a valid claim can be reduced or refused.
This guide explains how to claim marine cargo insurance in UAE ports and warehouses, the documents you will need, the time limits that matter and the mistakes that cost importers money. Your policy wording always takes priority, so read its claims conditions alongside this guide.
How to Claim Marine Cargo Insurance in UAE: The Six Steps
The steps below follow the standard claims procedure printed with the Institute Cargo Clauses and used by most cargo insurers in the UAE. Work through them in order, starting before the goods are signed for.
Step 1: Note the Damage Before You Sign
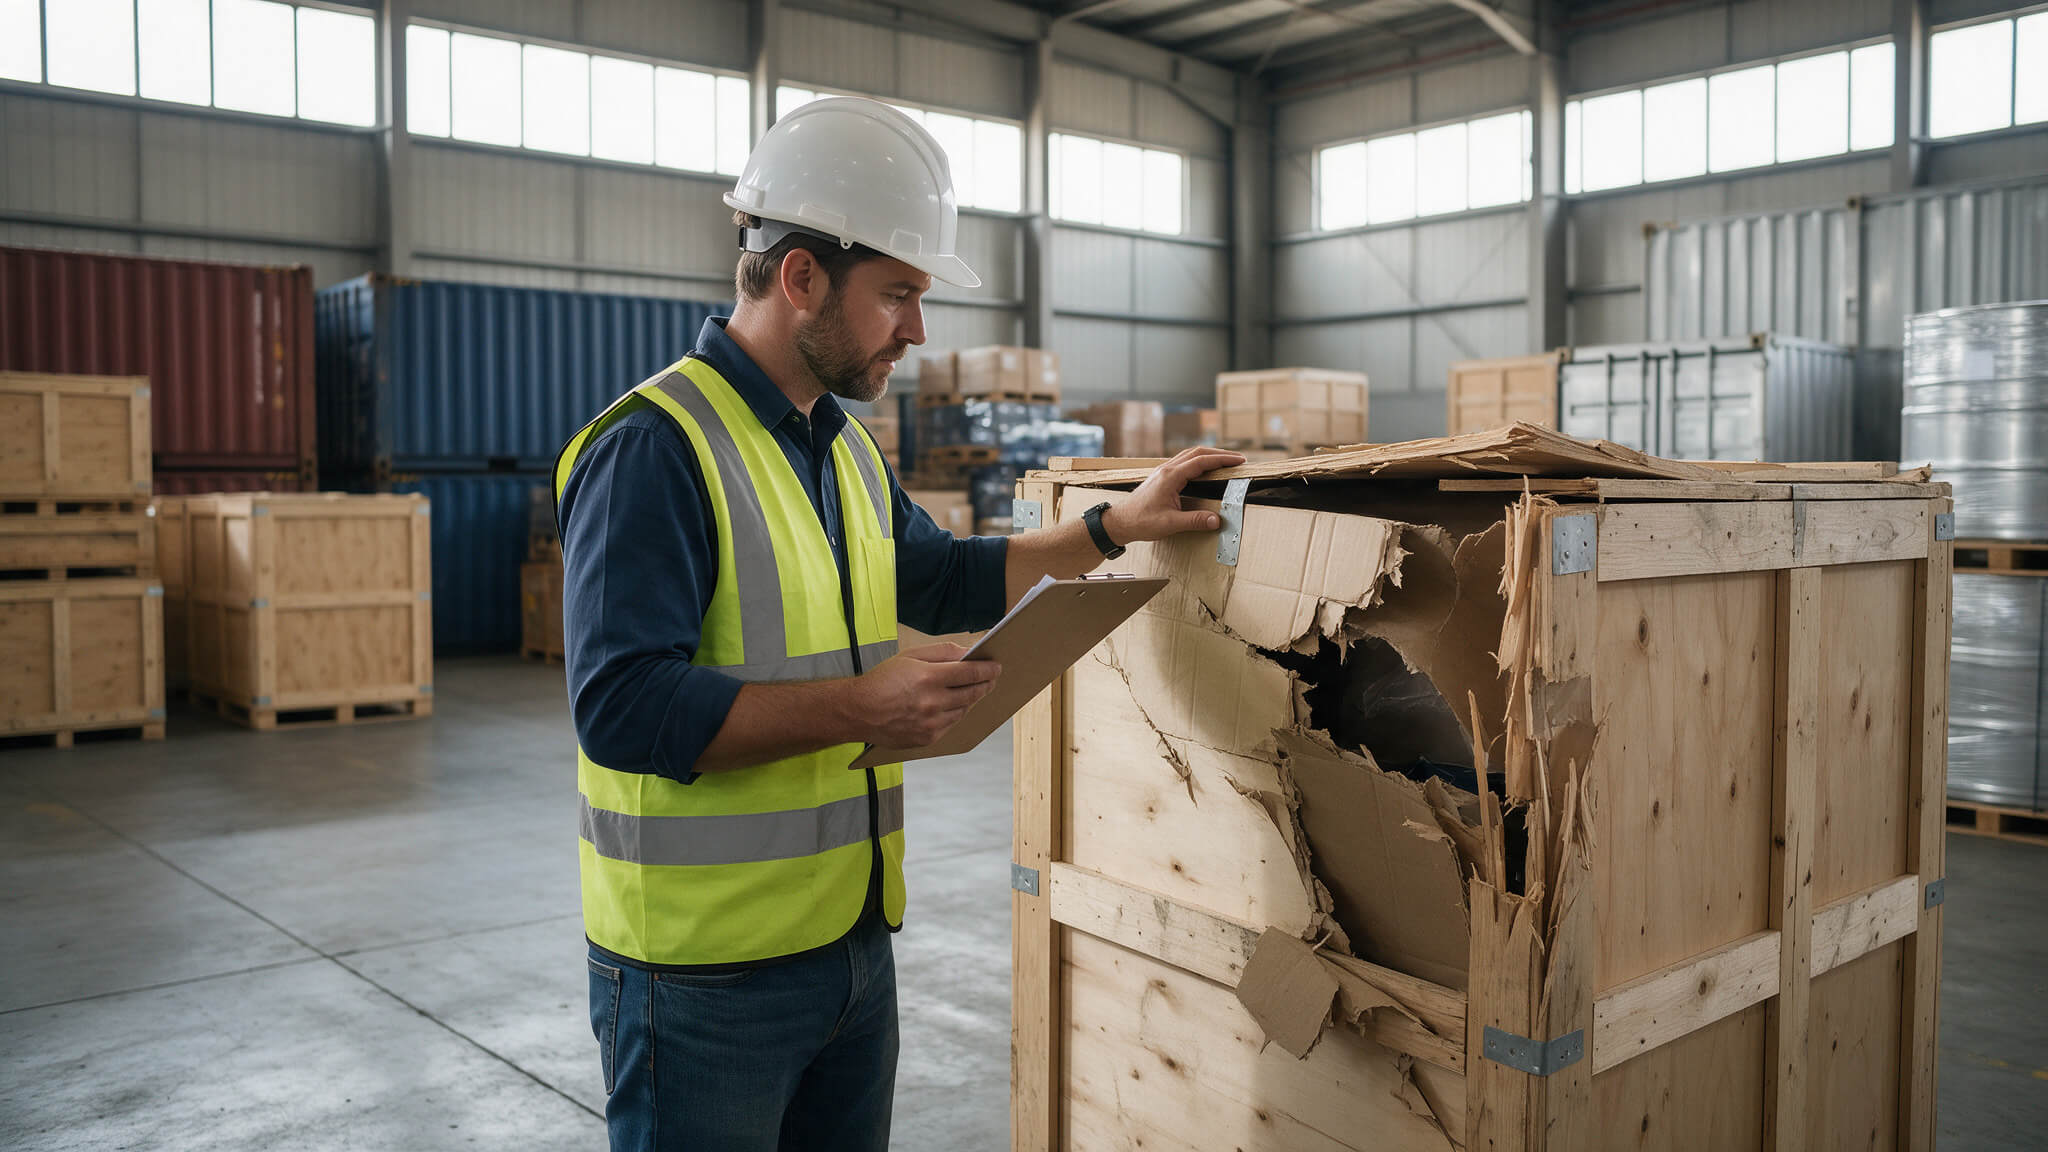
The single most damaging mistake is signing "received in good condition" before inspecting the cargo. A clean receipt is evidence that the goods arrived intact, which can wreck your insurer's right to recover from the carrier and weaken your own claim.
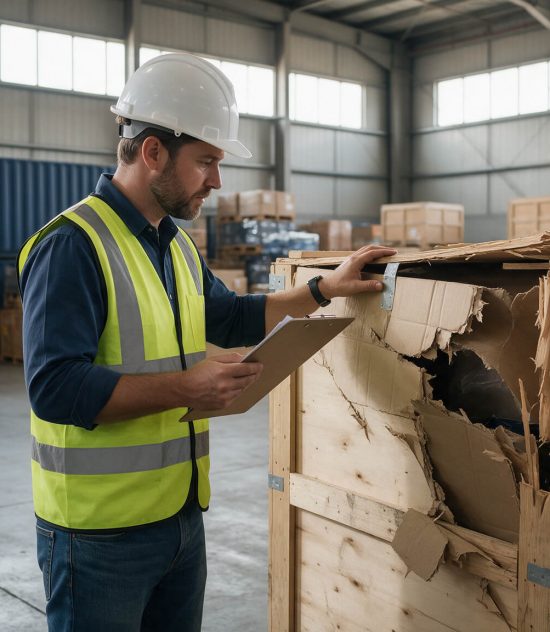
Before signing at Jebel Ali, Khalifa Port or your warehouse gate, check the container seal number against the bill of lading and look for dents, holes, wet patches or broken packaging. If anything looks wrong, write a specific remark on the delivery receipt or equipment interchange receipt, such as "container dented, contents not inspected" or "3 cartons wet", and photograph everything. If you cannot inspect, sign "unchecked" or "received under protest".
Step 2: Notify the Insurer Immediately
Tell your insurer or broker as soon as you discover the loss, ideally the same day. Most policies require prompt notice, and a late report can reduce or defeat a claim if it stops the insurer inspecting the goods.
Give the policy or certificate number, the bill of lading number, a short description of the damage and where the goods are now. Do not sell or throw away damaged goods until the insurer or surveyor agrees, but do take reasonable steps to stop the loss getting worse, such as moving cargo out of the rain.
Step 3: Arrange a Survey
Your insurance certificate usually names a survey or claims agent to contact. The surveyor inspects the goods, establishes the cause and extent of the loss, and issues a survey report that becomes the core of your claim.
Invite the carrier or its agent to a joint survey, ideally before the goods leave the port or container yard. If the shipping line declines to attend, keep its reply, as it shows you gave it the chance.
Step 4: Serve Notice on the Carrier
Put the carrier, and any port operator, warehouse or haulier that handled the goods, on written notice that you hold them responsible. Where loss or damage is not apparent at delivery, the Hague-Visby Rules require written notice to the carrier within three days.
This protects the recovery right your insurer takes over when it pays you. If that right is lost through your own inaction, the insurer may reduce your claim by the amount it could have recovered.
Step 5: Assemble the Document Pack
Gather the documents listed in the next section, together with your photographs and the survey report. A complete pack submitted in one go is processed far faster than one built up piece by piece.
If ASIB arranged your cover, you can submit your claim documents to ASIB online and our team will check the pack before it goes to the insurer.
Step 6: Submit and Track the Claim
Submit the pack with a claim bill: a statement of the amount you are claiming, calculated on the insured value. Keep a log of every exchange and answer any request for further information quickly.
If the insurer offers less than you expect, ask for its calculation in writing. Disputes can be escalated through the insurer's complaints process, then to the Central Bank of the UAE and SANADAK, the UAE's independent ombudsman unit for insurance and banking.
Documents You Will Be Asked For
Most cargo insurers ask for the following:
original policy or certificate of insurance
commercial invoice
packing list or weight notes
bill of lading or air waybill
survey report
claim bill setting out the amount claimed
carrier correspondence, including your notice of claim and any reply
delivery receipt or equipment interchange receipt showing your remarks
photographs of the container, seals, packaging and goods
Keep originals safe, as the insurer may need the original bill of lading to pursue the carrier.
Time Limits That Will Kill a Valid Claim
Several deadlines run at the same time, and missing any one of them can cost you the claim or the insurer's recovery.
Deadline
Applies to
What to do
On discovery of the loss
Your insurer
Notify the loss and request a survey
At delivery, or within 3 days if damage is not apparent
The sea carrier
Give written notice of loss or damage
Within 1 year of delivery
The sea carrier
Settle the claim, start proceedings or agree a written extension
60 days after discharge at the final port
Your cover, under standard transit terms
Clear and deliver the goods, or extend cover
Most bills of lading incorporate the Hague or Hague-Visby Rules, under which the carrier is discharged from liability unless suit is brought within one year of delivery. The UAE's own Maritime Law, Federal Decree-Law No. 43 of 2023, also sets a one-year limit for claims under a contract of sea carriage. Your insurer normally pursues the carrier, but only if you have given notice and passed on the documents in time.
For air freight, the Montreal Convention requires a written complaint within 14 days of receipt for damage, and legal action within two years.
Five Mistakes That Get Claims Reduced
Signing a clean receipt. "Received in good condition" on the delivery note is hard to undo and can wipe out the carrier recovery.
Disposing of goods or packaging too early. Without the evidence, the surveyor cannot confirm the cause or the extent of the loss.
Reporting late. Delays let damage get worse and make the cause harder to prove.
Underinsuring the cargo. If the insured value is below the real value, the claim can be reduced in proportion, so insure at CIF value plus 10%.
Settling with the carrier on your own. Accepting a payment from, or signing a release for, the carrier without your insurer's agreement can prejudice its recovery and reduce your claim.
What ASIB Clients Say
Two reviews from ASIB clients about claims support, reproduced exactly as posted on Google.
Have been dealing with Al Sayegh Insurance for the past few years. They provide immediate assistance and assist in settling insurance claims promptly. They also provide insurance premium details from multiple insurance companies, so that we can select a contract which address our major concerns and which will also fit our pocket. Great work and great team.
Nisha Y., Google review
I got very good support at the time of my car accident. Good team work.
Fouzul R., Google review
Frequently Asked Questions
How long do I have to make a marine cargo insurance claim?
Notify your insurer as soon as you discover the loss, as most policies require prompt notice. Separately, notice to the sea carrier is due within three days of delivery for hidden damage, and recovery action within one year.
What if I signed the delivery note without any remarks?
Tell your insurer and the carrier in writing as soon as you find the damage. Your own claim may still succeed, but a clean receipt makes recovery from the carrier much harder.
Does marine cargo insurance cover goods stolen from a container?
Under Institute Cargo Clauses (A), theft and non-delivery are covered unless an exclusion applies. Clauses (B) and (C) do not cover theft unless it has been added.
Can I claim for delayed cargo?
Not under standard cargo clauses, which exclude loss caused by delay even when an insured event caused it. Lost sales, demurrage and storage charges from a delay are not covered.
Who pays for the cargo survey?
For a valid claim, the survey fee is normally reimbursed as part of the claim. Check with your insurer or broker before instructing a surveyor yourself.
Talk to ASIB
A cargo claim is often won or lost in the first few days. If you are unsure how to claim marine cargo insurance in UAE for a particular loss, talk to an ASIB claims adviser before you sign anything or move the goods.
ASIB has operated in the UAE since 2003 and is registered with the Central Bank of the UAE (Registration No. 165). ASIB's marine insurance practice arranges marine cargo and goods in transit cover for importers and supports clients through claims. Cover terms and pricing are individually underwritten, regulations change, and nothing in this article is legal advice.
The ASIB Insurance Team writes these guides to help individuals and businesses in the UAE understand their cover before they need it. ASIB has arranged personal and commercial insurance in the UAE since 2003, with a team of more than 100 insurance professionals.